
EXC: Sharia financing is being adopted as official government policy across America.
I found dozens of examples of cities, states and federal regulators changing loan programs, tax rules, banking policy and economic-development plans to accommodate Islam.
Here’s the list 🧵
I found dozens of examples of cities, states and federal regulators changing loan programs, tax rules, banking policy and economic-development plans to accommodate Islam.
Here’s the list 🧵
Louisville, Kentucky: Louisville Metro rewrote its own small-business lending program to accommodate Islamic finance, announcing that METCO “will now offer a Sharia-compliant modification option.”
Minneapolis, Minnesota: Minneapolis openly offers city-backed business financing that it says “conforms with Islamic law.” The structure avoids conventional interest, uses shared risk and lender profit, and can be matched with city financing.
Saint Peter, Minnesota: Saint Peter’s Economic Development Authority restructured a municipal loan around Sharia lending rules, making it “structured to eliminate interest payments” and replacing interest with a 3.25% “profit.”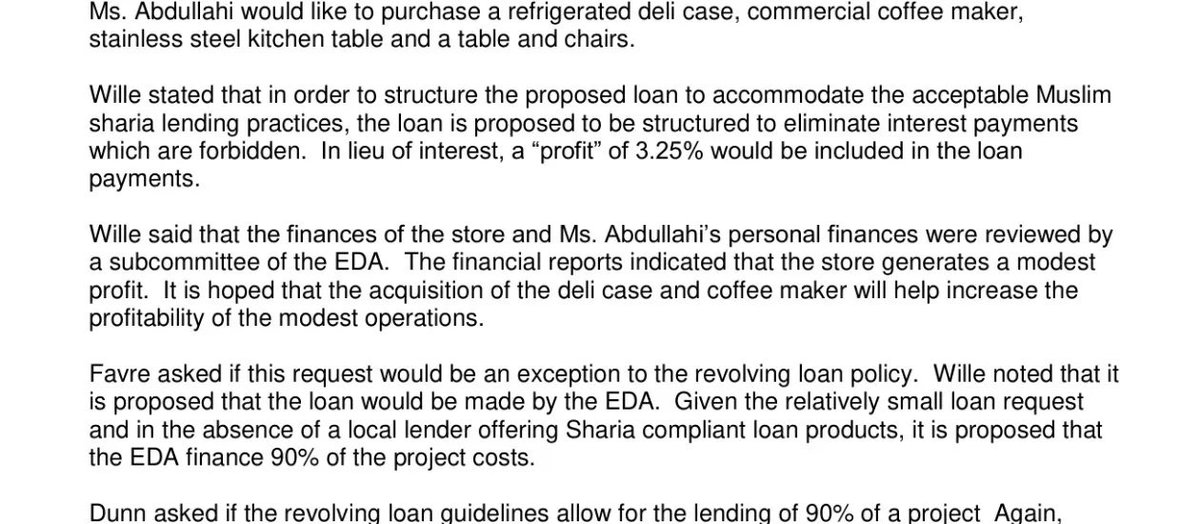
Lewiston, Maine: Lewiston says the city and CEI actually provided Islamic-law-compatible commercial financing through “interest free loans with service charges.”
Maine: Official Maine legislative testimonysays state law was changed so state-chartered credit unions “can now offer Sharia-compliant mortgage loans.”
Philadelphia, Pennsylvania: Philadelphia’s official housing plan literally calls on the city to “Develop a Sharia-compliant Financing Product.” Islamic financing was made an explicit municipal housing-policy objective.
Seattle, Washington: Seattle’s mayoral housing plan created an official action item titled “Housing Tools for Sharia-Compliant Lending” and committed the city to expanding access to those products.
Seattle, Washington: Seattle’s Office of Immigrant and Refugee Affairs separately told the city to “Research alternative Islamic financing loan options” and explore government initiatives around them.
Seattle, Washington: Seattle EDI advisory-board minutes show officials discussing “turning [funding] into a sharia-compliant loan fund.” The minutes establish that city officials considered the proposal, not that the fund ultimately launched.
Washington State: Washington’s Department of Commerce explicitly recommends developing “Sharia-compliant financial products” for underserved businesses.
Washington State: A separate Commerce report to the legislature incorporates “Sharia-compliant financing for capital projects”into state economic-development planning.
Winooski, Vermont: Winooski’s FY2027 city workplan tells officials to “Encourage financial institutions to create Islamic financing vehicles” and advocate for their development.
Hamtramck, Michigan: Hamtramck’s 2025 Economic Recovery Plan includes a section explicitly titled “Sharia-Compliant Loan Product,” identifying Islamic financing for possible deployment in the city.
Auburn, Maine: Auburn’s official consolidated plan says municipal officials had worked on “Sharia acceptable commercial loans.”
Minnesota: Minnesota’s Department of Revenue maintains dedicated guidance for “Shariah Compliant Home Financing”explaining how filers can “avoid the payment of MRT on the profit portion” of the transaction.
Federal Reserve: The Federal Reserve’s current Regulation K guidance expressly addresses whether certain Islamic-finance arrangements are permissible and recognizes qualifying purchase-and-repurchase structures under federal banking rules. The FAQ is current guidance, although it draws on an older underlying interpretation.
Federal Reserve: The Federal Reserve’s current Regulation K guidance expressly addresses whether certain Islamic-finance arrangements are permissible and recognizes qualifying purchase-and-repurchase structures under federal banking rules. The FAQ is current guidance, although it draws on an older underlying interpretation.
Clallam County, Washington: Clallam County’s government website directs residents to “Islamic Financing” options. The county is not originating the financing, but its official government resource system is directing residents toward it.
Tukwila, Washington: A Tukwila public record says a business client “Needed Sharia compliant funding,” prompting the publicly supported SBDC to work with lenders offering Sharia financing.
Washington County, Oregon: Washington County’s economic-development websiteactively advertises “two types of Shari’a-compliant financing” to local businesses.
St. Louis Park, Minnesota: St. Louis Park’s official business-support website directs entrepreneurs to providers specifically offering “Sharia-compliant financing.”
Edina, Minnesota: Edina’s city business-assistance page promotes two separate Islamic-finance sources, advertising NDC’s “Sharia-compliant financing” and telling businesses that ADC has “Sharia-compliant funding… available.”
Saint Paul, Minnesota: Saint Paul’s official CAPER says participating business owners can receive financial advice, financing leads and “Sharia banking if relevant.”
Federal OCC / Project REACh: The same OCC initiative highlighted banks working together on “Sharia-compliant commercial opportunities,” putting Islamic commercial financing inside a federal financial-inclusion initiative.
Federal OCC advisory committee: OCC advisory-committee minutes explicitly discuss the need for “Islamic/Sharia financing” in Minnesota and banking partnerships designed to provide it.
Full story on @Substack here!
• • •

Replies